For an NRI selling property in India, finding a buyer
and completing the registration can feel like the difficult part. Then comes a
question many sellers do not think about until the transaction is almost over:
how do you actually move the sale proceeds from India to the country where you
now live?
Consider a simple example. An Indian living in the United
States sells an apartment in India for ₹1 crore. The buyer completes the
required tax deduction, the sale deed is registered and the money reaches the
seller’s Indian bank account.
The seller now wants to transfer the money to a US bank
account.
At this point, the transaction changes from a property
sale into a cross-border remittance. The bank may want to know where the money
came from, how the property was acquired, whether the applicable Indian taxes
have been reviewed and whether the proposed remittance complies with India’s
foreign exchange rules.
This is where many NRIs encounter delays they were not
expecting.
Selling property and moving money are separate processes
Property
registration proves that the property has been transferred. It does not, by
itself, establish that the entire amount can immediately be remitted overseas.
For
India-sourced money, an NRO account is commonly part of the process. Under the
RBI framework, eligible NRO balances and certain eligible assets can generally
be remitted up to USD 1 million per financial year, subject to the relevant
conditions and the authorised dealer bank’s review.
For
a seller with proceeds below this level, that may sound straightforward.
But
the limit is only one part of the process.
The
bank still needs to establish the source of funds and whether the tax and FEMA
requirements relating to the transaction have been addressed. Two NRIs selling
properties of similar value can therefore have very different experiences.
One
may complete the transfer without much difficulty because the documentation is
organised. Another may face repeated requests for old purchase documents, tax
records or proof explaining how the property came into the family.
The buyer’s TDS does not
necessarily complete the tax process
necessarily complete the tax process
Tax
deducted by the buyer is important, but NRIs should not assume that the
deduction automatically settles every tax question connected with the sale.
The
seller’s actual capital gains position depends on factors such as the
acquisition cost, ownership history, eligible expenditure and other facts
specific to the transaction.
The
TDS appearing in Form 26AS or other tax records also needs to match the
property transaction correctly.
If
excess tax was deducted, the seller may eventually claim the eligible refund
through an Indian income tax return. If additional tax is payable, that needs
to be addressed separately.
For
the remittance, the bank may ask for supporting tax records before allowing the
money to move abroad.
This
is one reason it helps to organise the tax file while the property sale is
taking place, rather than several months later.
Old documents can suddenly
become very important
become very important
Property
that was purchased many years ago can create another problem.
The
seller may have the current sale deed but struggle to locate the original
purchase deed. In inherited property cases, the trail can be more involved. The
bank or tax professional may need documents that establish how ownership passed
from the original owner to the current seller.
Depending
on the facts, this could involve a Will, probate documents, succession records,
legal-heir documentation, family settlement papers or other evidence of
ownership.
A
missing document that did not prevent the property from being marketed can
still create questions later when the seller tries to establish the source and
tax history of the money.
The bank is doing more
than processing a wire transfer
than processing a wire transfer
An
overseas transfer of property sale proceeds is not simply a normal bank
transfer.
The
authorised dealer bank has its own compliance responsibilities. It may review
the account from which the funds are being sent, the source of the money, the
purpose of the remittance, tax documentation and the FEMA route being used.
Depending
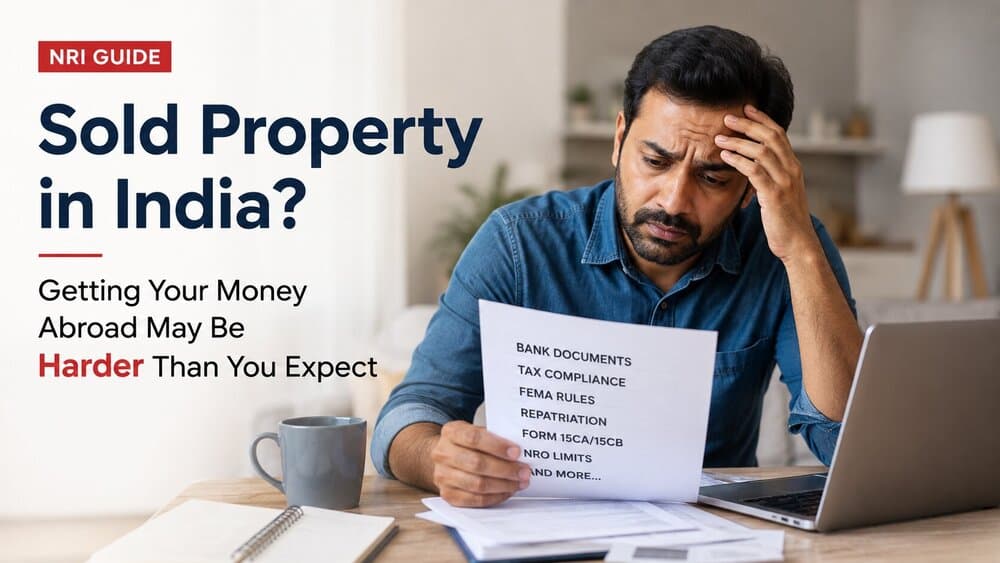
on the transaction, Form 15CA and a Chartered Accountant’s certificate may also
become relevant. The exact requirement depends on the nature of the remittance,
its tax treatment and the applicable rules.
Banks
can also have their own document checklists and internal procedures.
This
explains why advice such as “just transfer it from your NRO account” can be
misleading. The account is only one part of the file.
The
underlying transaction must also make sense.
Preparation before the
sale can save weeks later
sale can save weeks later
An
NRI who knows that the eventual goal is to move the proceeds abroad should plan
for that before the property transaction closes.
The
seller should preserve the original ownership documents, registered sale deed,
buyer payment trail, TDS records, relevant bank statements and the records used
for the capital gains calculation.
Inherited
property should receive additional attention because the ownership trail may
need to be established before the remittance file is complete.
The
seller should also speak with the bank that will handle the eventual transfer.
Asking for the bank’s property-sale repatriation checklist in advance can
expose missing documents while there is still time to obtain them.
That
is much easier than discovering the problem after the money is already sitting
in an NRO account and an overseas payment is due.
Need help transferring property
sale proceeds abroad?
sale proceeds abroad?
If you have sold
property in India, or are preparing to sell, Cross Border Tax Desk offers a
free 10-minute call with a Chartered Accountant.
You can use the call to discuss your property sale, TDS position, NRO funds, tax documentation and the steps that may be required before transferring eligible proceeds overseas.
What if the amount is more than USD 1 million?
Large
transactions need additional planning.
The
RBI’s general NRO remittance framework provides for eligible remittances up to
USD 1 million per financial year. The limit can cover eligible balances and
assets considered within that framework, rather than simply each property sale
separately.
Sellers
dealing with larger amounts should therefore understand the available route and
timing before making commitments about when the full proceeds will reach an
overseas account.
The
exact treatment will depend on how the property was acquired, how the funds are
held and the applicable FEMA conditions.
Inherited property
deserves special attention
deserves special attention
Many
NRIs do not purchase the Indian property they eventually sell. They inherit it
from parents or other relatives.
These
transactions can involve three separate questions at the same time.
First,
does the seller have a clean ownership trail?
Second,
what is the correct Indian tax treatment when the inherited property is sold?
Third,
what documents will establish the source and eligibility of the funds when the
money is eventually remitted overseas?
Looking
at only the sale deed can miss the bigger picture.
The
inheritance documents, historical acquisition records and later sale records
may all become part of the same financial trail.
Think about the
destination of the money before you sell
destination of the money before you sell
For
NRIs, selling Indian property should ideally be planned backwards.
Start
with the final objective.
If
the objective is to keep the money in India, the banking plan may be relatively
simple.
If
the objective is to send the proceeds to the United States, United Kingdom,
UAE, Canada, Australia or another country, the seller should think about the
tax and repatriation file before the sale is completed.
The
property transaction may take place in India, but the financial journey often
does not end there.
For
many NRIs, the last stage of the sale is not handing over the keys.
It
is getting the money where they actually need it.
For
a detailed guide, visit Cross Border Tax
Desk’s guide to repatriating property sale proceeds from India.
About Cross Border Tax Desk
Cross Border Tax Desk assists NRIs with India-side tax, property-sale documentation, TDS, FEMA and repatriation matters. Readers can use the form above to request a free 10-minute introductory call with a Chartered Accountant.
This article provides
general information only. Tax, FEMA and banking requirements depend on the
facts of each transaction. Readers should obtain advice based on their specific
circumstances before acting.