Now, rather than just scoring properties, I would like to occasionally write about the way of thinking when evaluating properties. In this article, I will explain one of the indicators I value most when assessing properties:
a realistic approach to ‘land value (actual market land value)’.
If you are a salaryman landlord who has already started investing or studying (with an annual income of 8 million yen or more and financial assets of 10 million yen or more as a benchmark), you likely already know that ‘land evaluation’ is important in real estate investment. However, if you blindly believe that ‘properties with high land appraisal are the only righteous ones’ based on knowledge from books published several years ago, there is a danger that you will not be able to buy any properties in the current market or that you will fall into unexpected traps.
I hope to deliver practical insights that will help improve the resolution of your investment criteria, while incorporating the underlying philosophy of my unique ‘land and asset value evaluation’ logic.
Although it is a unique logic, I am proud to say that it is a way of thinking that firmly grasps the core of real estate investment, arrived at after daily, gritty verification.
Building value will eventually become zero. Why is ‘land value’ the most important?
Real estate consists of ‘buildings’ and ‘land,’ but in my logic, I evaluate the ‘building value as zero’ and thoroughly measure only the value of the land.
This is because buildings are depreciated year by year, and both in terms of tax law and actual asset value, their value eventually heads toward zero. Of course, even wooden structures can be lived in for over 50 years without problems if properly maintained, but the bank’s collateral evaluation and the perspective of other investors when selling in the future will be extremely severe.
That is precisely why ‘land value,’ which does not deteriorate over time, becomes extremely important.
The closer the actual market land value is to the selling price, the lower the possibility of being underwater on your remaining debt at the time of a future exit (sale). Even if you assume a ‘worst-case scenario’ where the building is completely destroyed by fire or natural disaster, this actual market land value functions as a ‘lower limit (safety net)’ for the assets remaining in your hands (*In reality, if you sell it as land, there are demolition costs to make it vacant land and eviction costs if there are tenants, so land value does not equal the net proceeds as is, but higher land value is always better).
Roadside land prices are not the actual value. The concept of ‘multiplier’ and the reality of the market
When measuring land value, the ‘roadside land price’ (rosenka) determined by the National Tax Agency is generally used. Bank collateral evaluations (land appraisal) are also basically based on this.
However, in the actual real estate market, land is not traded at the roadside land price. What is truly important is the ‘actual market land value’ that is actually bought and sold in the market.
Usually, the actual market price is calculated by working backward from recent neighborhood transaction cases, but general investors cannot always conveniently confirm the ‘latest transaction price of land with identical conditions.’ Therefore, in my logic, I calculate a hypothetical actual market land value using a ‘unique multiplier coefficient’ that reflects the market supply and demand balance based on the roadside land price.
In the current market centered on the Tokyo metropolitan area, land values are soaring. Especially in prime locations such as city centers and areas near stations where the ‘roadside land price is high,’ the actual transaction price (actual market value) deviates significantly upward from the roadside land price. To capture this market reality, my logic uses an algorithm that applies a multiplier close to 1x for areas with low roadside land prices, and gradually higher multipliers (up to 1.5 to 1.6 times the roadside land evaluation) for areas with higher roadside land prices. Actually, this multiplier can be applied to a certain extent, but for ultra-prime locations that exceed the upper limit, the sky is the limit, so I do not really consider those areas as targets.
Based on my experience so far, the ‘hypothetical actual market land value’ calculated with this logic is often very close to actual neighborhood transaction cases, and it functions very effectively as an important indicator for investment judgment.
Do not swallow books completely! The trap of ‘100% land appraisal’ and the position talk of real estate agents
If you read real estate investment books from a while ago (2-3 years ago or more), it is sometimes written that ‘properties where the land appraisal is close to 100% of the selling price are treasure properties’ or ‘aim for properties with a land value ratio of 100% or more.’
However, I will state clearly: in the current market, the probability of a general investor encountering a property in the city center or its suburbs where the land appraisal is at that level and a certain amount of cash flow (CF) can be expected is almost zero. Even if it appears on the market, agents with financial power will snatch it up instantly behind the scenes.
What you want to be careful about here is the sweet temptation from real estate agents. Among the agents, there is a certain number of salespeople who will aggressively push ‘old properties in the suburbs that have low roadside land prices (usually less than 100,000 yen) but have unusually large land and bulky buildings’ using the plausible logic that ‘to continue to get loans from banks and expand your scale, it is best to buy properties that have collateral evaluation (appraisal).’
However, you should not swallow that logic.
First, a high assessed value means that the annual ‘fixed asset tax and city planning tax’ will weigh heavily on you in proportion to that value. Furthermore, since most of these properties are located in the suburbs far from stations, you will always be plagued by anxiety regarding not only current tenant acquisition but also future rental demand.
And above all, the fatal flaw is the ‘low cost-effectiveness of repairs.’ Large suburban properties have low rent per unit, yet the rooms are spacious, and the building surface area and rooftops are vast. Therefore, the cost of large-scale repairs such as exterior wall painting and waterproofing becomes enormous, and there is an extremely high risk that invisible maintenance costs will fly away like water relative to rental income.
Of course, I believe there are excellent properties out there, but I think many of these proposals heavily reflect the position-talk of agents who ‘somehow want to get rid of large, low-liquidity, hard-to-sell suburban properties.’
At first glance, the bank’s collateral appraisal (land assessment) might appear high, but the actual demand value (actual market land value) is significantly lower. You should also consider the possibility that it is a trap where you won’t find a buyer when you want to sell in the future, or in the worst case, it could become a ‘game of Old Maid where you can’t sell even if you want to.’
The ‘Optimal Solution’ for Salaryman Landlords and the Criteria for Proprietary Logic
So, what kind of properties should we, as salaryman landlords, be targeting?
It is a ‘property that isn’t perfect, but is a decent property with a balance between cash flow and actual market land value.’ In my proprietary logic, I have specifically set the following lines as a ‘benchmark for realistic competition.’
-
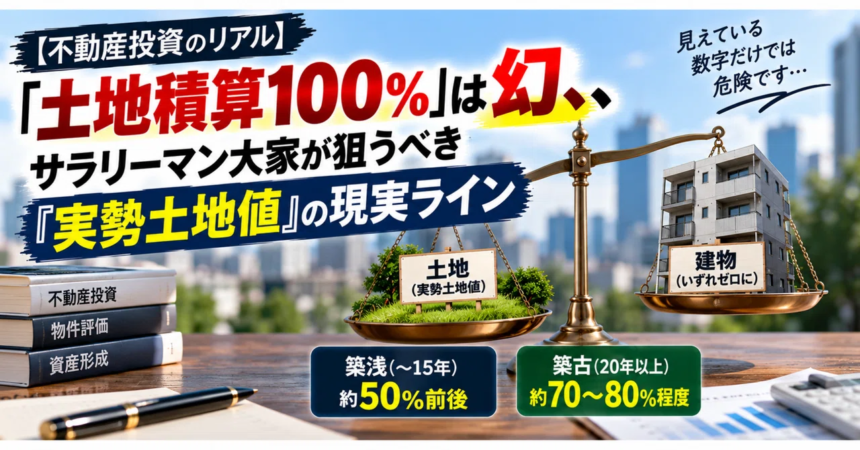
For relatively new buildings (as a guideline, within 15 years old): Use the actual market land value being around ‘50% of the selling price’ as a guideline. Naturally, the closer it is to a new build, the lower it may be. If it is a relatively new building, the value of the building itself is heavily factored in, so it is a market principle that the proportion of land value decreases. If the location is not bad and a certain level of cash flow is secured, it is by no means a bad level.
-
For older buildings (as a guideline, 20 years or older): You want the actual market land value to be around ’70-80% of the selling price.’ Since the value of the building has eroded, if the majority of the selling price is not backed by the value of the land, the risk of the remaining debt exceeding the value in the future increases.
I believe that picking up properties that meet this line and are in locations where tenant acquisition is not a problem (good walking distance to the station and access to terminals) is the shortcut to an investment that doesn’t lose.
Also, for land, not only ‘size and road rating’ but also ‘shape and road access’ are vital. In my logic, wide-frontage rectangular lots or corner lots are evaluated positively, but I apply penalty deductions for ‘flag-shaped lots,’ ‘lots with only private road access,’ ‘lots where the front road is extremely narrow,’ or ‘properties built on retaining walls’ as risks of being severely beaten down on price at the exit, because they may incur huge costs during future reconstruction or be difficult to finance.
A final word
In real estate investment, dream properties that offer both ‘high yield (cash flow)’ and ‘perfect land assessment’ do not exist in the general market.
That is precisely why it is important to understand the gap between the road rating and the actual market price (the concept of the multiplier) and to identify the ‘line you can compromise on’ according to the building age and location. By continuing to look at over 100 properties every day and repeatedly dealing with agents in a gritty manner, the possibility of finally encountering a ‘decent, excellent property that you can bet on after factoring in the risks’ increases.
※Disclaimer: The way of thinking about land valuation and the proprietary assessment criteria in this article are based solely on the author’s subjective views and experience, and do not guarantee the certain asset value or investment results of real estate. I cannot take any responsibility for decisions made by referring to this article.
How was it? I hope that the way of thinking about ‘actual market land value’ in this article will be an opportunity for you to update your criteria for choosing properties. If you felt that it was ‘helpful’ or ‘would like to see other analyses or actual property assessments,’ please ‘like’ and ‘follow’ me! It will be a great driving force for my daily gritty research and article writing.