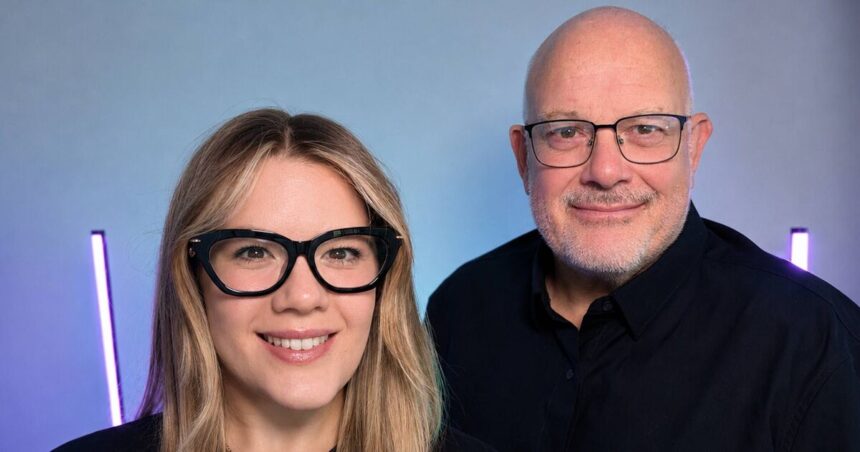

Hannah and Peter Vandervennin of The Mortgage Consultancy (Image: Newspage)
Property investors are being advised to carefully plan their exit strategy from bridging finance before committing to it, as inadequate planning can transform an otherwise sound investment into a costly problem. Bridging loans serve as short-term financing solutions and prove especially valuable when investors require swift action, need to purchase at auction, undertake renovation projects or acquire properties that don’t immediately meet standard mortgage criteria.
Hannah Vandervennin, director and mortgage adviser at The Mortgage Consultancy, stressed that investors shouldn’t be apprehensive about bridging finance. However, they must evaluate the complete transaction from the beginning, rather than concentrating solely on securing funds as rapidly or economically as possible.
She said: “Bridging has sometimes got a reputation for being expensive or scary, but used properly it can be an incredibly powerful tool. We use it to help clients buy at auction, fund works, move quickly on opportunities, break chains and solve situations that conventional mortgages simply can’t. The key is understanding the whole transaction before you start and working with people who understand both the bridge and what comes afterwards.”
Hannah highlighted that one of the most significant errors investors could commit was presuming there was just one method of structuring a transaction. She recently examined a scenario where a client required approximately £50,000, yet the current arrangement involved considerably more borrowing spread across two properties.
She said: “When we looked at the wider circumstances, there appeared to be another route using a smaller second-charge bridge against one property, which would have carried materially lower costs. That’s why the structure matters as much as the rate. With bridging, you need to understand exactly what you are trying to achieve, what security is available, how much you genuinely need to borrow and what happens at the other end.”

Experts have given advice (Image: Jacob Wackerhausen via Getty Images)
Exiting a bridging loan typically involves either selling the property or switching to longer-term financing once renovation or development work has been completed. Nevertheless, even the most thoroughly planned property venture can run into unforeseen difficulties, which is why Hannah advises having multiple potential exit strategies in place.
She recalled a case involving an investor converting a property into a house in multiple occupation (HMO). The borrower anticipated the finished property would reach a specific valuation, enabling them to refinance and settle the bridging loan.
However, the final valuation came in considerably below expectations, rendering the original exit strategy far more difficult to execute.
Hannah said: “Nobody necessarily did anything wrong. The valuation simply came in differently from what had been expected and that’s exactly why you need a Plan A, Plan B and ideally a Plan C.
“If you’re relying on refinancing, you need to ask what happens if the valuation comes in lower. What happens if the works cost more than expected? What happens if lending criteria or the mortgage market change while you’re doing the project? You want to have those conversations before taking the bridge, not when you’re already on short-term finance and suddenly discovering your planned exit doesn’t work.”
The Mortgage Consultancy consequently examines both the initial bridging finance and the probable subsequent outcomes when counselling investors.
Hannah added: “A well-planned bridge should give you options and help you move forward. If the structure, numbers and exit have all been properly thought through, there’s no reason investors should be frightened of it.
“The mistake isn’t using bridging finance. It’s going into it without properly understanding the whole journey.
“Getting the money is only the beginning. The important question is where the bridge is taking you and how you’re going to get there.”