Around 84% of the operational portfolio held by India’s existing listed REITs and real-estate InvIT is office space. It is a useful number for understanding both how far the market has come and how much room remains for it to change.

Offices gave Indian REITs a natural starting point. Large business parks could provide long leases, established tenants and recurring rental income, while institutional ownership had already created portfolios large enough to bring to the public market. The result is visible today: Colliers estimated in June 2026 that around 164 million sq ft of office assets were already held under existing REITs, with office REIT penetration at about 19% of India’s office stock.
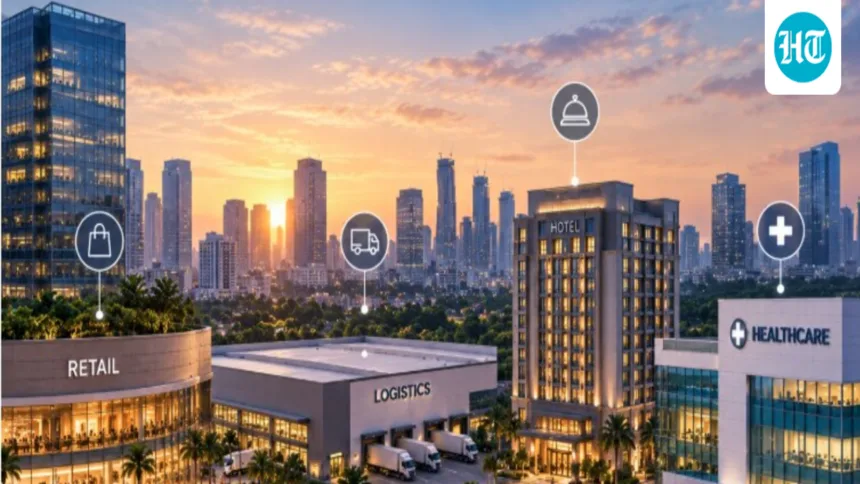
But a REIT market does not have to remain an office market. Retail is already represented in India’s listed REIT universe, while institutional capital is building positions in logistics, hotels, healthcare and other forms of real estate. The question for the next phase is which of these assets can provide the income characteristics needed to move from an interesting property sector to a credible part of the listed real-estate market.
Retail has already crossed the line
Retail offers the clearest Indian example of diversification actually taking place rather than simply being discussed. Nexus Select Trust brought a retail-focused portfolio to the listed REIT market, breaking the office-only pattern.
The underlying property market has continued to expand. JLL recorded 6.27 million sq ft of gross retail leasing across India’s top seven markets in the first half of 2026, up 10.5% from 5.68 million sq ft a year earlier and the highest half-year leasing volume in four years. Shopping-mall vacancy fell from 11.60% to 11.15% over the same period.
There is also more space being built. JLL estimates that approximately 45.5 million sq ft of shopping-mall space is under various stages of construction across the top seven cities and is expected to become operational by 2030.
Diversification needs more than a different label on a building. A listed vehicle needs a sufficiently large pool of assets with tenants, cash flows and operating histories. A growing stock of organised malls can increase that pool, although individual properties will still differ substantially in tenant mix, footfall, lease structures and performance.
Warehouses are building institutional scale
Warehousing presents a different case. India already has a listed industrial and warehousing vehicle, but it is structured as an InvIT rather than a REIT. That distinction should not be lost when assessing the direction of the property market.
What the sector does demonstrate is increasing institutional ownership of logistics real estate. CBRE found that 33% of new warehousing supply in the first half of 2026 was institutionally backed. Third-party logistics companies accounted for 31% of absorption, while engineering and manufacturing occupiers contributed another 26%. Delhi-NCR, Chennai and Bengaluru together represented around 60% of leasing.
For listed real estate, warehouses have characteristics that can be attractive at scale: leased space, business tenants and demand linked to supply chains, manufacturing, e-commerce and third-party logistics. They also bring risks that differ from offices. Location depends heavily on transport infrastructure and industrial clusters, while tenant requirements and lease economics can vary by facility.
The significance, therefore, is not that warehouses are destined to become the next Indian REIT category. It is that the sector is developing the institutional ownership and operating history from which future listed structures can potentially emerge.
Hotels and hospitals come with different economics
Hospitality and healthcare widen the discussion further because both involve property whose performance is closely tied to an operating business.
Indian hotels are currently benefiting from relatively firm demand. ICRA estimates premium hotel occupancy at 72–74% in FY2026 and expects it to remain in that range in FY2027. Average room rates are projected to rise from ₹8,200–8,500 in FY2026 to ₹8,600–8,800 in FY2027, while industry revenue is forecast to grow 7–9%.
Healthcare is expanding too. ICRA’s sample of listed hospital companies recorded occupancy of 63.5% in FY2026, alongside an 18% increase in revenue. It expects revenue growth of 13–15% in FY2027 as operators add beds and new capacity gradually ramps up.
Neither set of figures means hotels or hospitals automatically belong in Indian REIT portfolios. They illustrate the operating conditions of sectors attracting real-estate capital. A hotel room is not leased like an office floor, and hospital economics depend on factors including occupancy, pricing, clinical mix and operating efficiency.
Any future listed-property model therefore has to account for the relationship between ownership of the building and operation of the business inside it.
Residential needs a different definition
Residential real estate is another category where size alone can be misleading. India has a vast housing market, but homes built primarily for individual sale do not naturally produce the recurring rental income associated with conventional REIT portfolios. The more relevant comparison with developed REIT markets is professionally managed, income-producing residential property. That can include apartment portfolios, student accommodation and other rental-living formats.
The distinction is important because a successful housing-sales market does not by itself create a residential REIT pipeline. For that to happen, India would need sufficiently large portfolios held for rental income, supported by professional management and operating data.
The regulatory framework also places income generation at the centre of the existing REIT model. SEBI’s rules require at least 80% of the value of REIT assets to be invested in completed, rent and/or income-generating properties, with no more than 20% in other permitted assets.
That makes the availability of mature income-producing assets more important than the headline size of any property sector.
Mature markets show how broad the definition can become
The US offers an indication of how far the model can eventually stretch. Thirty years ago, traditional sectors such as office, retail, residential, industrial and diversified REITs accounted for roughly three-quarters of the FTSE Nareit All Equity REITs Index by market capitalisation. By 2026, newer and emerging categories including data centres, healthcare, telecommunications, gaming, lodging and resorts, self-storage, timberland and specialty real estate, represented just over half. The index itself reached about $1.5 trillion in market capitalisation in 2026.
The sectors do not behave alike, including when measured by income yield. Nareit data recorded on September 17 2026 put dividend yields at 4.45% for US office REITs, 4.71% for retail, 3.54% for industrial, 4.19% for residential, 4.01% for lodging and resorts and 2.54% for healthcare. The overall FTSE Nareit All Equity REITs Index yielded 3.80%.
These figures are not benchmarks for what Indian REITs or individual Indian properties should yield. Capital costs, lease structures, taxation, property values and market conditions differ. What they demonstrate is that diversification does not produce one uniform REIT economics. Investors can encounter different combinations of income, growth, operating sensitivity and property risk within the same listed structure.
Diversification will depend on the assets underneath
India still has considerable room to expand within offices themselves. Colliers estimates that roughly 370 million sq ft of existing office stock could potentially be included in future REIT portfolios, led by Hyderabad and Bengaluru. Its broader assessment nevertheless expects listed REIT and real-estate InvIT structures to expand further into areas such as industrial and warehousing property and retail.
That suggests diversification is unlikely to mean offices being displaced. More plausibly, the listed market can become broader while its original asset class continues to grow.
Retail has already demonstrated that an Indian REIT need not be office-only. Warehousing is showing how institutional ownership can develop in another rental property category. Hotels and hospitals have large operating platforms but introduce different business risks, while residential would require a deeper stock of professionally managed rental assets before the comparison with mature residential REIT markets becomes convincing. The experience of larger REIT markets also suggests that the eventual opportunity can extend well beyond the property categories that dominate at the beginning.
For India, however, the order does hold significance. A sector does not become suitable for a REIT simply because investment is flowing into it. It first needs assets capable of producing recurring income, portfolios large enough to achieve scale and operating records that investors can assess.
India’s REIT market may therefore become more diversified gradually, one pool of mature assets at a time. Offices built the first chapter because they were ready. The next one will be written by whichever property sectors reach that point next.
Note to the reader: This article has been produced on behalf of the brand by HT Brand Studio and does not have journalistic/editorial involvement of Hindustan Times.