Hello everyone.
I am a financial planner and a father raising a mischievous 1.5-year-old son.
Now, I often receive consultations like this from people who own their own homes or are thinking about buying one.
“My parents told me to pay off my mortgage early no matter what, but is that true?”
“Interest rates are rising, so should I switch to a fixed-rate mortgage right now?”
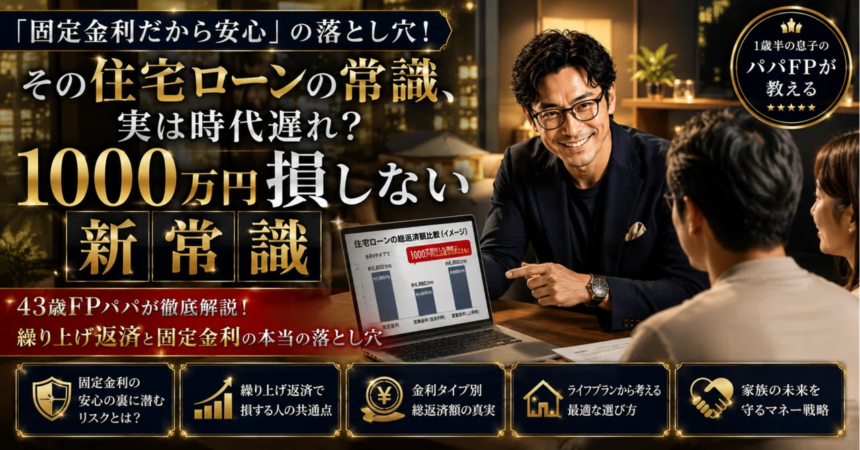
If you act based on the conventional wisdom from the old ‘ultra-high interest rate era’ or ‘non-inflationary era,’ you might actually end up depleting your cash on hand or missing out on returns you could have earned through investment, leading to losses in the tens of millions of yen.
In this article, let’s unravel the new common sense for mortgages that fits today’s interest rate environment.
1. Let’s discard the common sense of the Showa and Heisei eras! The pitfalls of ‘early repayment’
A while ago, when mortgage interest rates were 5% or 7%, ‘paying off the loan early to reduce interest’ was the ultimate savings technique.
However, in today’s era of continued low interest rates, if you force yourself to make early repayments and reduce your cash on hand, the following risks arise.
-
Loss of liquidity (cash) on hand: You will no longer have reserve funds for children’s education, sudden illnesses, or job changes. Once you have used money for early repayment, you cannot easily borrow it back from the bank.
-
Opportunity cost: Rather than paying off a loan with a low interest rate (e.g., around 0.3% to 0.5%), it is better to invest that capital long-term in index funds with an expected return of 4% to 5% through programs like the ‘New NISA,’ which will create a larger asset difference in the future.
In our household, we prioritize securing education funds and reserve expenses as our 1.5-year-old son grows, and we strictly follow a style of keeping cash (liquidity) on hand while putting money into asset management.
2. The misconception that ‘fixed rates are absolutely safe’
As news of rising interest rates increases, more people are panicking and asking, ‘Should I switch from a variable rate to a full-term fixed rate?’
It is true that fixed rates offer peace of mind because the repayment amount does not change, but the interest rate spread between them and variable rates has already widened significantly.
-
The risk of continuing to pay high insurance premiums: Choosing a high fixed rate from the start can be seen as ‘continuously paying a high monthly insurance premium (the interest rate difference) from the beginning against potential future interest rate hikes.’
-
Know your household’s ‘tolerance’: Rather than simply changing the interest rate type, the first priority is to understand the numbers: ‘How much will the monthly payment increase if interest rates rise by 1%?’ and ‘Can your current household budget or investment returns cover that increase?’
3. ‘3 New Common Sense Rules for Mortgages’ that 40-something parents should review right now
-
Make full use of group credit life insurance (Danshin) as ‘smart coverage’: Mortgages come with comprehensive group credit life insurance (such as cancer coverage or 3 major disease coverage). Since it also functions as coverage in case of an emergency, it is modern to utilize your cash on hand while receiving this coverage rather than forcing yourself to pay off the loan early.
-
Do not force repayment during the mortgage deduction period: During the deduction period, maximize the tax-saving benefits and let the remaining funds grow quietly in investment accounts like the New NISA.
-
Plan ‘repayment’ and ‘investment’ as a set: Instead of thinking about the mortgage in isolation, it is important to balance ‘debt’ and ‘invested assets’ within your overall household asset allocation.
A mortgage is not just ‘debt’; if managed wisely, it becomes a ‘leverage tool’ that can powerfully support your family’s lifestyle and future asset building.
Just as historic, old townscapes have incorporated the latest technology of each era to survive into the present, we should also flexibly update our household management to match the latest information.
In our home, we are also keeping a firm eye on the future of our one-and-a-half-year-old son while continuing to plan our finances in a way that is sustainable and secure for us as a couple.
Let’s take it one step at a time, without rushing!
🎁 [We look forward to having you join our membership!]
Thank you for reading until the end today.
As an FP dad raising a one-and-a-half-year-old son, I hope I have been able to provide useful tips for daily life from the perspective of an ordinary household.
If you feel like ‘I want to learn more with everyone’ or ‘I want a place where I can get individual consultations,’
please join our membership, ‘Financial Planner Consultation Room’.
We offer two styles of membership to suit your goals.
🟢 Everyone’s FP Consultation Room (980 yen/month)
・Exclusive articles and real-life reports on FP asset building
・Unlimited access to past articles & Q&A/interaction on the exclusive bulletin board
・Simple advice once a month in the ‘Everyone’s FP Consultation Room’
🔵 FP Consultation for Your Own Finances (3,980 yen/month)
・All benefits of the Standard Plan included
・’Individual FP Consultation’ tailored to your annual income, family structure, and asset status
(Personalized consultations on household budget, NISA, education expenses, insurance, mortgages, etc., are available)
*This service was launched as a formal way to properly address the individual consultations I have been receiving.
Whether you want to ‘learn with everyone’ or ‘have an FP consult on your own household budget directly,’ you are very welcome!
Let’s find the ‘just right’ investment and household budget that will help your family sleep soundly at night and stay happy.
I look forward to talking with you!
👉 [Click here for membership details and to join]
Information | Financial Planner Consultation Room | Financial Planner Consultation
If you want to know the golden ratio of asset allocation practiced by an FP and the strategies involved, please see this pinned article.
👉‘Better than reading 100 books on the “branches and leaves” of investment, read this one. The complete bible on “asset allocation” and “investor psychology” to make global economic growth your own household’s wallet’ | Financial Planner Consultation
#Mortgage #EarlyRepayment #FixedInterestRate #VariableInterestRate #NewNISA #HouseholdBudgetImprovement #FPConsultation #ParentingHouseholds #MoneyStudy #AssetBuilding