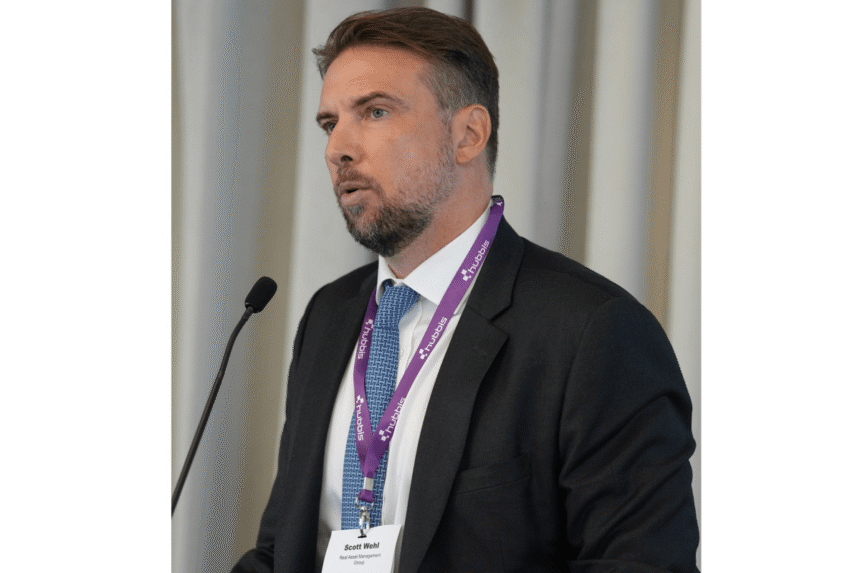
At the Hubbis Investment Forum – Hong Kong 2026, Scott Wehl, Founder and Executive Chairman of Real Asset Management Group (RAM®), outlined opportunities in Australian mortgage credit and essential-services real estate. The Sydney-headquartered manager reported approximately HK$52 billion in assets under management (AUM) across more than 25 strategies as at 31 August 2026.
Australia combines strong sovereign ratings and considerable household wealth with continued population growth. Above-target inflation, a 4.35 per cent cash rate at the time of the forum (since raised to 4.60 per cent), softer home prices and changes to housing taxation make the position less straightforward.
RAM favours diversified credit backed by Australian real property, , grocery-anchored shopping centres and modern healthcare property. The firm aims to give high net worth (HNW) investors and family offices access to the same assets as institutional investors.
Key Takeaways
- Sovereign Strength Supports Credit: Australia retains AAA ratings from S&P, Moody’s and Fitch, supporting its domestic credit and currency case.
- Household Wealth Adds Resilience: Median wealth was estimated at almost US$211,000 per adult in 2026, although that aggregate strength does not remove pressure on highly indebted borrowers.
- Migration Sustains Demand: Australia added 392,700 people in the year to March 2026, keeping pressure on an undersupplied housing market.
- Rates Remain A Live Risk: Inflation remained above the Reserve Bank of Australia’s target, and RAM expected further tightening before eventual cuts.
- Housing Is Adjusting: National prices were down almost 4 per cent year on year by mid-September, with larger falls in Sydney and Melbourne as borrowing costs and policy changes weighed on sentiment.
- Mortgage Structures Matter: Full-recourse lending, conservative underwriting and subordination have helped investment-grade Australian residential mortgage backed securities (RMBS) avoid capital losses historically.
- Essential Services Lead Property: RAM prefers property tied to recurring local demand, particularly grocery-anchored shopping centres and community-based healthcare facilities.
- Private Wealth Can Invest Alongside Institutions: RAM gives HNW investors and family offices access to the same assets as its institutional clients, subject to each product’s terms.
Sovereign Ratings and Household Wealth
Australia is one of nine countries carrying AAA ratings from all three major agencies. Real gross domestic product (GDP) grew 2.1 per cent in the year to June 2026, while unemployment was approximately 4.5 per cent.
UBS estimated median wealth at nearly US$211,000 per adult in 2026, about three times the US level and the third-highest figure in its global ranking. High mortgage debt and living costs still leave some borrowers exposed.
The Australian dollar can also diversify currency exposure. “Australia is one of the few liquid, highly rated currencies through which investors can diversify away from the US dollar,” Wehl said. RAM’s longer-term view placed it around US$0.74, compared with approximately US$0.71 on 22 September. Currency movements can increase or reduce overseas returns.
Migration and Interest Rates
Australia added 392,700 people in the year to March 2026, of whom 292,100 came through net overseas migration. The pace has eased from its post-pandemic peak, yet still supports demand for homes, shops and healthcare.
Headline inflation reached 3.8 per cent in the year to June, while trimmed-mean inflation was 3.6 per cent. Both exceeded the Reserve Bank of Australia’s (RBA) 2 to 3 per cent target band. At the time of the forum, RAM expected one or two further 25-basis-point increases to the 4.35 per cent cash rate by the end of 2026, followed by possible cuts around mid-2027. The RBA has lifted the cash rate to 4.60 per cent on 29 September 2026. This was RAM’s house view, rather than RBA guidance.
Housing Prices and Policy Changes
Australia’s mortgage market is worth about A$2.6 trillion, making housing central to both household finances and the credit system. By mid-September 2026, national home prices had fallen almost 4 per cent over 12 months. Sydney and Melbourne were down more than 7 per cent, while Perth remained firmer.
Measures announced in May restrict negative gearing for newly acquired established homes from July 2027. They also replace the 50 per cent capital-gains-tax discount with indexation and a 30 per cent minimum tax on real gains. Existing holdings were grandfathered for negative gearing, while qualifying new construction retained concessions. The Australian Prudential Regulation Authority (APRA) had already introduced a debt-to-income lending limit in February.
The changes may weaken investor demand and borrowing capacity without correcting years of underbuilding. For credit investors, the combination of falling prices and persistent housing demand puts more weight on borrower selection and collateral quality.
Why Mortgage Credit Can Remain Resilient
RMBS turn pools of home loans into bonds with different levels of risk. Australia’s securitised market is worth about A$240 billion, making it one of the world’s larger markets outside the United States and United Kingdom, excluding onshore China.
Australian mortgages are generally full recourse, lending standards are closely supervised, and each security can contain thousands of geographically dispersed loans. Junior capital absorbs losses before senior bondholders. Investment-grade Australian RMBS have not recorded capital losses, although future losses remain possible.
Payment behaviour has also been supportive. “Australian households tend to protect the mortgage payment first and cut discretionary spending before they allow the loan to fall behind,” Wehl said. Fitch placed 30-day-plus arrears in prime Australian RMBS at 1.18 per cent in the first quarter of 2026. RAM reported arrears below 0.5 per cent in its own mortgage book, a portfolio figure rather than a market-wide measure.
RAM’s Mortgage Credit Strategy
Floating-rate assets can preserve income as policy rates rise, although borrowers must meet higher repayments. RAM backs non-bank lender Brighten Home Loans (Brighten®), which originates about A$450 million to A$500 million of mortgages a month. This supplies diversified credit portfolios with a continuing flow of loans.
RAM’s credit strategies are underpinned by Brighten’s 11,500 first-ranking mortgages, which recorded 90 Day+ arrears of just 0.52 per cent as at 31 July 2026, compared with 1.63 per cent for the S&P Non-Conforming SPIN. RAM said its relevant credit funds had recorded no credit losses or drawdowns in net asset value (NAV) in nine years.
One of its credit strategies, the RAM Real Income Fund, targets the RBA cash rate plus 4 per cent after fees,equivalent to a target return of 8.60 per cent per annum at the current cash rate, with distributions paid monthly. Returns are not guaranteed, and withdrawals may be delayed or suspended when liquidity is limited.
Essential Services in Commercial Property
RAM concentrates on property serving recurring local needs. Nearly two million additional people are projected to be employed in Australia by May 2035, expanding demand for neighbourhood retail and healthcare services.
Grocery-anchored centres benefit from regular footfall and relatively defensive spending. RAM also pointed to yields of around 8 per cent in parts of commercial property and historically low correlation with equities. Results depend on the property, tenant quality and financing.
Community Healthcare Property
Australia’s ageing population and the shift of treatment away from large hospitals are changing healthcare property. RAM focuses on facilities combining general practitioners, specialists, diagnostics and day procedures close to where patients live.
“These are not the 500-bed hospitals of old,” Wehl said. “They are community health centres where patients can see a GP, a specialist and a surgeon in one place.” Longer leases and the operational importance of the premises can support durable income, but development execution, tenant concentration and valuation risk remain.
The RAM Australia Healthcare Opportunity Fund is an open-ended property vehicle for wholesale and professional investors. The firm reported a cumulative gross return of 30.44 per cent from 1 March 2024 to 31 July 2026 and targets a gross total return of 16 to 18 per cent. Past returns are not a reliable indicator of future performance. Target returns are not guaranteed.
Institutional Assets for Private Wealth
The practical appeal lies in accessing diversified mortgage pools and specialist real estate without managing each asset directly. “Our aim is to let high net worth investors and family offices invest alongside institutional clients,” Wehl said.
Institutional participation does not make every structure suitable. Investors must still examine fees, leverage, valuation and redemption terms. For RAM, Australia’s strong fundamentals create the opportunity, while careful selection of the underlying loans and properties determines the outcome for investors.