
NEWS ANALYSIS | URN | The real estate sector is one of those facing stiff demand, with the current supply side far below capacity, mainly due to financing.
Finance Minister Henry Musasizi last week said this required private investment and financing that households and developers can afford, also suggesting that Mortgage refinancing could help lenders provide longer-term housing finance.
However, there is a cheap and easy financing option, that Ugandans have not yet taken advantage of: the Real Estate Investment Trusts (REITS). This is where investors can pool resources which are then invested in a property, under regulation by the Capital Markets Authority.
Basically working like the now popular unit trusts, it needs not much by one to become an investor.
However, the explanations by the market leaders, fund managers and CMA suggest that it is developers that are yet to come on board to list their properties and raise capital from the public through the REITs.
The REITS are provided for under the Collective Investments Schemes Act and the REITs regulations made in 2017. Close to 10 years later, CMA says that no developer has applied to put their asset into any REIT, which is a cheap way to raise capital.
Knight Frank, one of the largest real estate managers in Uganda, says that the REITs market is not yet attractive to developers for various reasons including regulatory, taxation and competitiveness. Marc du Toit, Head of Retail at Knight Frank Uganda, says the Ugandan real estate market is ready for REITs, considering the interest by corporate companies, individuals going it alone and those doing it in groups, especially Ugandans in the diaspora.
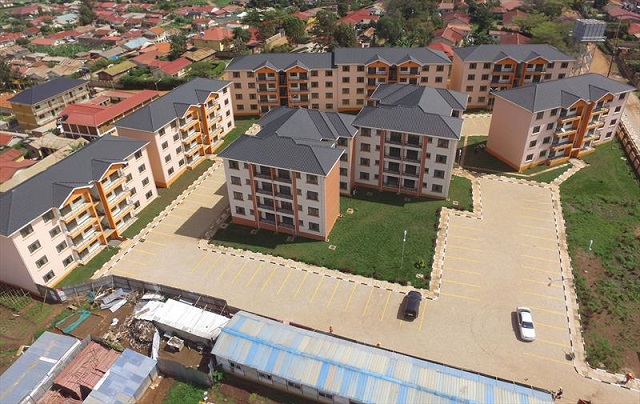
He points out warehouses, large malls and apartments in and around Kampala as well as residential estates countrywide but adds that the sector still needs a lot of capital for the market to be satisfied. Available capital sources, especially the banks, are too expensive.
However, du Toit points at the environment that has not encouraged formalisation of the market, including the ‘discouraging’ tax regime, the alternative investment options that offer higher returns, among others.
Yet, he adds, the informality in the sector has also led to disputes among group or joint investors because corporate governance frameworks are missing, leading to lengthy legal battles and further keeping capital away.
Ronald Kasolo, Vice President of Find Managers Association of Uganda and also CEO at Kura Asset Management agrees, adding that fund managers prefer to invest people’s money where returns are predictable, corporate governance is credible and a proper exit strategy exists.
He adds that fund managers are also not willing to invest the CIS funds into real estate where returns can only go as high as 13%, yet the government offers 10-year bonds at 15.2 percent net of taxes.
Kura has been engaging anchor investors in real estate to embrace REITs especially for the sake of diversification of investment.
Kasolo also cites competitive returns compared to government treasuries, and issues related to real estate like revenue collections culture, and inflation adjusted income rates.
Du Toi says that 10 years of the existence of a REITs regulatory framework without registering any development is not a Uganda case, as the same happened in developed markets like Kenya and South Africa, while in the US, it took almost 30 years.
According to the Association of Real Estate Agents of Uganda, taxation is one of the main hindrances to growth. Shirley Konga mentions Stamp Duty when purchasing land; Capital Gains when acquiring property; VAT and other fees when developing the plan; the charges by authorities when approving the plan; VAT on all materials during construction; rental income tax and property tax when building is completed; Capital Gains Tax when selling it.
Yet, she adds, interest paid on acquiring funds for development is not an allowable deduction.
Dickson Ssembuya, CMA Director for Research and Market Development at CMA, agrees that the industry and other relevant government agencies must work on outstanding issues if REITs is to take off in Uganda.
These include taxation, especially Stamp Duty and Capital Gains Tax when a property is being transferred; lack of proof of concept in the market; a proper and credible governance terrain; and public awareness.
This, he says is the time to make the market operational especially as commercial banks credit is becoming more expensive and scarcer.
In Kenya, for example, the real estate sector under the REITs regulations is exempt from Capital Gains Tax and Stamp Duty to encourage developers to put their assets into this market.