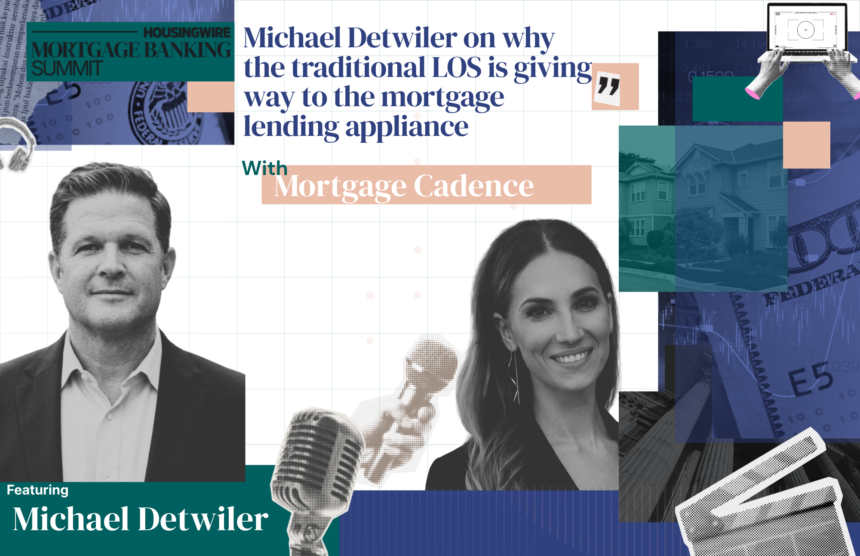
In a conversation with HousingWire’s Allison LaForgia, Mortgage Cadence CEO Michael Detwiler discussed why he returned to the company, how agentic AI could reshape mortgage operations and why the traditional loan origination system may be giving way to a more automated mortgage lending appliance.
Detwiler returned to Mortgage Cadence with the same goal that helped launch the company more than two decades ago: automating the mortgage process. “When we started the business, our whole idea was to automate the mortgage process, so we embedded a rules engine into our LOS, and the whole idea is it should be better, it should be more predictable, it should be faster,” Detwiler said.
After leaving the business in 2018, advances in technology gave him a reason to return. “With all of the advances in tech, particularly around agent capabilities, I thought we really can finally achieve the vision that we had back in the early 2000s,” he said. “And so I came back to lead that charge for Mortgage Cadence.”
Moving beyond highly customized systems
One obstacle to that vision, Detwiler said, is how lenders have historically implemented new technology. Instead of redesigning the process, teams often recreate the workflows they already know. “They implement new technology with the same processes that they brought along with them in their journey through mortgage,” he said. “I think that’s why we end up with a lot of fragmented and highly customized implementation.”
In many cases, the problem begins with not knowing what a true fresh start could look like. “People don’t, in many instances, don’t really know what the fresh start might be,” he said. “They don’t have that vision.”
Detwiler believes a different model could eventually replace the traditional LOS. “I would say that the traditional LOS is replaced by a loan origination system appliance,” he said.
Like a household appliance, the system would already understand how to execute much of the work rather than requiring extensive configuration. “It’s a system that already knows how to handle very specific processes, how to automate them, how to order services, how to handle the channel that the particular lender is in, the type of product that the lender is offering and do it in an automated way,” he said. “It doesn’t have to be customized. It doesn’t have to be programmed, it doesn’t have to be configured. It’s out of the box.”
“The goal is a compliant mortgage at the end of the process.”
Selling certainty instead of speed
Greater mortgage automation could also let lenders spend more time acquiring and retaining borrowers. But Detwiler believes that requires shifting the industry’s focus from speed alone to certainty. “I think there’s a misunderstanding about the difference between certainty and speed,” he said. “Setting expectations and meeting those expectations is really what satisfies a borrower.”
Consumers have already been conditioned to expect that visibility in other transactions. “Everything we do every day is driving that and feeding and fueling that expectation,” Detwiler said. “You order on Amazon, you get an email that says it shipped. You get an email that says it’s on its way. You get an email that says it’s delivered.”
“Consumers and customers are going to demand the exact same thing for mortgage and already are doing it.”
For Detwiler, the lesson for lenders is clear: “They sell certainty, and consumers buy certainty.”
Building quality control into the process
Agentic AI could also fundamentally change mortgage quality control, but only if lenders address the complexity of their underlying systems first. “Agents do not work well in chaos,” Detwiler said.
Rather than adding agents to disconnected platforms, he envisions them operating within a mortgage lending appliance, validating data and services throughout the loan process. “When you have agents in your system that are validating when a service was ordered, that are analyzing the data in the system of record against the data that came in from a service order, that’s extracting the data and matching it, you’re basically building QA QC into the process,” he said.
Humans would remain involved where their judgment is most valuable. “Have the human in the loop for high-risk decisions or exceptions only,” he said.
That structure, Detwiler believes, creates the possibility of “100% quality control on every loan that comes out of a system.”
From AI experimentation to implementation
Although interest in agentic technology is accelerating, Detwiler said the mortgage industry has yet to fully transition from testing AI to embedding it in production. “I think that people are still experimenting,” he said. “I think that they’re going to have to move from experimentation to actually implementation.”
Simply introducing AI agents is not enough. “Agents are only going to do what your technology allows them to do,” he said.
For Detwiler, lenders need to reconsider assumptions about how mortgage production has traditionally operated. “People still think of the mortgage industry as having to be a certain way, and it doesn’t have to be a certain way,” he said. “It has to be compliant at the end.”
That opens the door to a model centered on automated operations, continuous quality control and a more predictable borrower experience. “The fastest way that you’re going to get there is by automating your back office and automating the underlying chaos of your technology,” Detwiler said. “You accept the technology that allows you to produce compliant mortgages and 100% QC, and then you market and collect your borrowers by selling certainty.”
“That’s what I believe the future of the mortgage business is.”