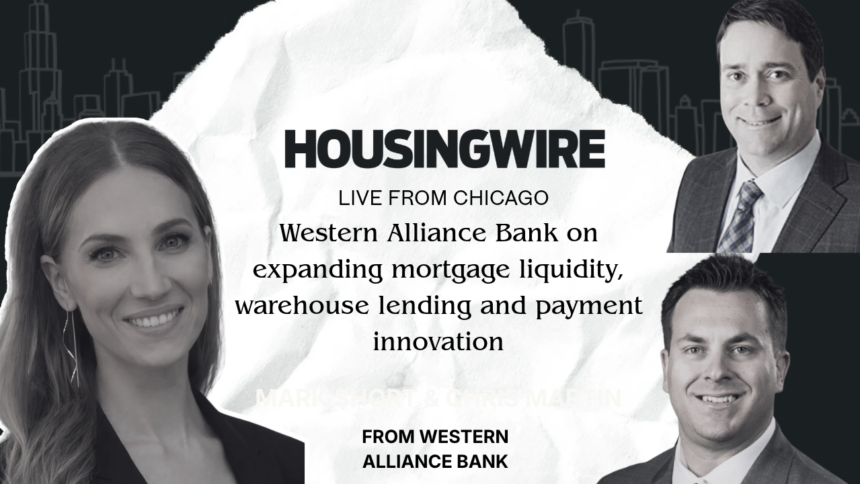
In a conversation with HousingWire’s Allison LaForgia, Western Alliance Bank’s Mark Short, National Sales Manager of Mortgage Warehouse Lending, and Chris Martin, Director of Treasury Management Sales, discussed how the bank is expanding its specialized mortgage services, strengthening lender relationships and investing in payment technology.
The two leaders shared how flexible financing, collaboration and a commitment to mortgage lending are helping Western Alliance identify growth opportunities amid challenging market conditions.
A comprehensive approach to mortgage warehouse lending
Short explained how Western Alliance’s Specialized Mortgage Services group brings multiple financing solutions together to support clients across the mortgage ecosystem. “We started off in 2009. So we’ve been doing warehouse financing for 17 years,” Short said. “Then we added MSR financing. So we’ve been doing that for 13, 14 years, and then we have another group inside that division called Note Finance, where we lend to private lenders.”
He also highlighted the bank’s acquisition of AmeriHome, its whole-loan purchasing capabilities and dedicated treasury management team. “I think that sets us apart a little bit from most banks because it all sits in one division,” Short said.
Adapting mortgage liquidity solutions to market uncertainty
Martin emphasized that listening to clients and offering flexible financing structures remain central to Western Alliance’s strategy. “We’re in a challenging environment right now with the rate environment, and I think what Western Alliance does really well is we’re active listeners of our clients and what they need,” Martin said. “We try to be flexible and creative in our lending structures to help our clients achieve their ultimate goal and drive up originations.”
Short pointed to opportunities for greater collaboration through AmeriHome’s customer relationships, including expanding warehouse lending to smaller independent mortgage banks. “We’re starting to reach out to those customers with smaller warehouse lines and provide the same benefits that I just talked about with the pricing,” Short said. He also identified loan syndication as an opportunity as mortgage industry consolidation continues.
As for Martin, he reinforced the bank’s long-term commitment to mortgage finance. “Other banks have gotten out of the space, and we just continue to dive in through good times and bad. Be creative and continue to grow inside the ecosystem of mortgage because the bank really loves mortgage,” Martin said.
Building a culture that supports growth
As Western Alliance expands, Short said maintaining the bank’s culture and developing future mortgage leaders remain priorities. “When I started six years ago, we’re a $40, $45 billion bank, and now we’re approaching $100 billion. So the challenge is trying to keep our culture together while you’re growing,” Short said.
He emphasized the importance of bringing younger professionals into warehouse lending and teaching them how to serve clients. “We’re trying to kind of educate the younger generation about the space, and then just teach them about our culture by being in the office,” Short said.
The next opportunity: Mortgage payment technology
Looking ahead, Martin identified embedded payment technology as a major opportunity for Western Alliance. “Over the last four years, [we] have been really focused on what partners we want to integrate with and embed the bank payment rails behind those technologies to create a frictionless payment environment,” Martin said. “I think the next evolution of the bank is to be a large remittance provider in the payment space inside the ecosystem of mortgage.”
Short concluded by emphasizing how Western Alliance’s leadership structure enables the bank to respond quickly to changing client needs. “When something happens in the industry, we can move quicker than the other bank because it’s like a quick phone call to the executive team,” Short said. “I’ve been at the bank six years. We’ve always been really quick to adapt to changes.”