The outlook across the UK commercial real estate market became more cautious in September, as concerns over inflation and interest rates dampened the sector’s fragile hopes of a recovery, according to Savills.
Prime yields across office subsectors and the industrial sector moved out by 25 basis points, while industrial multi-let yields remained unchanged. This took the average prime yield to 6%, the largest monthly outward movement since November 2023 and the highest level since October 2024.
Savills’ report reveals UK government bond yields remaining at multi-decade highs and renewed inflation concerns triggered expectations that interest rates would remain higher for longer. It says that with additional uncertainty existing ahead of the Autumn Budget, optimism seen earlier in the year had been tempered.
Retail yields, however, remained stable, with comparatively attractive entry yields and strong income returns, according to Savills.
The firm reported £3.8bn worth of central London office assets under offer at the end of Q3, with signs that investors remained interested at the start of Q4, typically a busy final quarter.
Ronald Dickerman, president of investment firm Madison International Realty, said in a LinkedIn post that the uncertain rate environment was continuing to “create opportunities in the secondaries market” while commercial real estate valuations and borrowing costs remained in flux.
He told the Financial Times that the only “logical conclusion is that real estate values have to fall”. The FT reported that several investors that went under offer in the summer were seeking discounts due to lower real estate values and higher financial costs.
Savills added that while demand within the occupier market remained robust, the outlook for prime office supply looked increasingly bleak, both in central London and across the major regional cities. Across the big six regional markets, deliveries scheduled for 2027 and 2028 currently total 1.05m sq ft a year, approximately 32% below the five-year annual average.
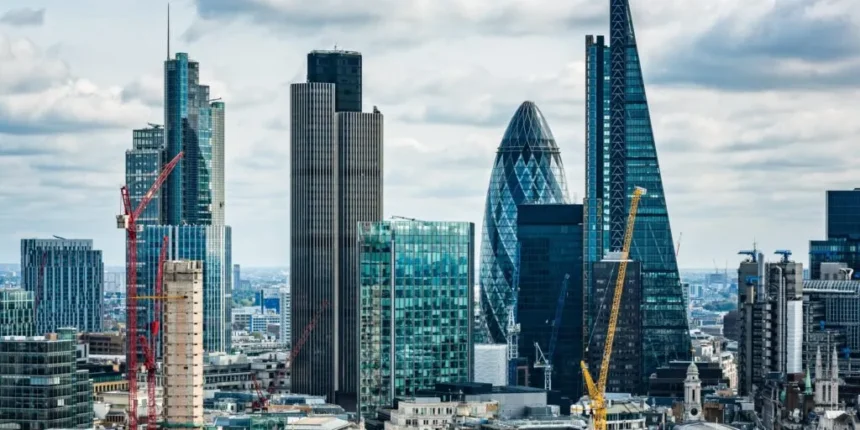
By contrast, central London’s near-term development pipeline appears more substantial, with completions set to reach a record 7m sq ft this year. Overall, 15.3m sq ft is currently under construction, with 64% due to complete by the end of 2027 and 25% already let ahead of completion.
New starts have slowed significantly in 2026, and further cost pressures are expected to place additional strain on the viability of new development. Savills highlighted that no new ground-up office schemes started in central London during Q3.
The challenge is “increasingly one of converting planned supply into deliverable space”, the firm added.